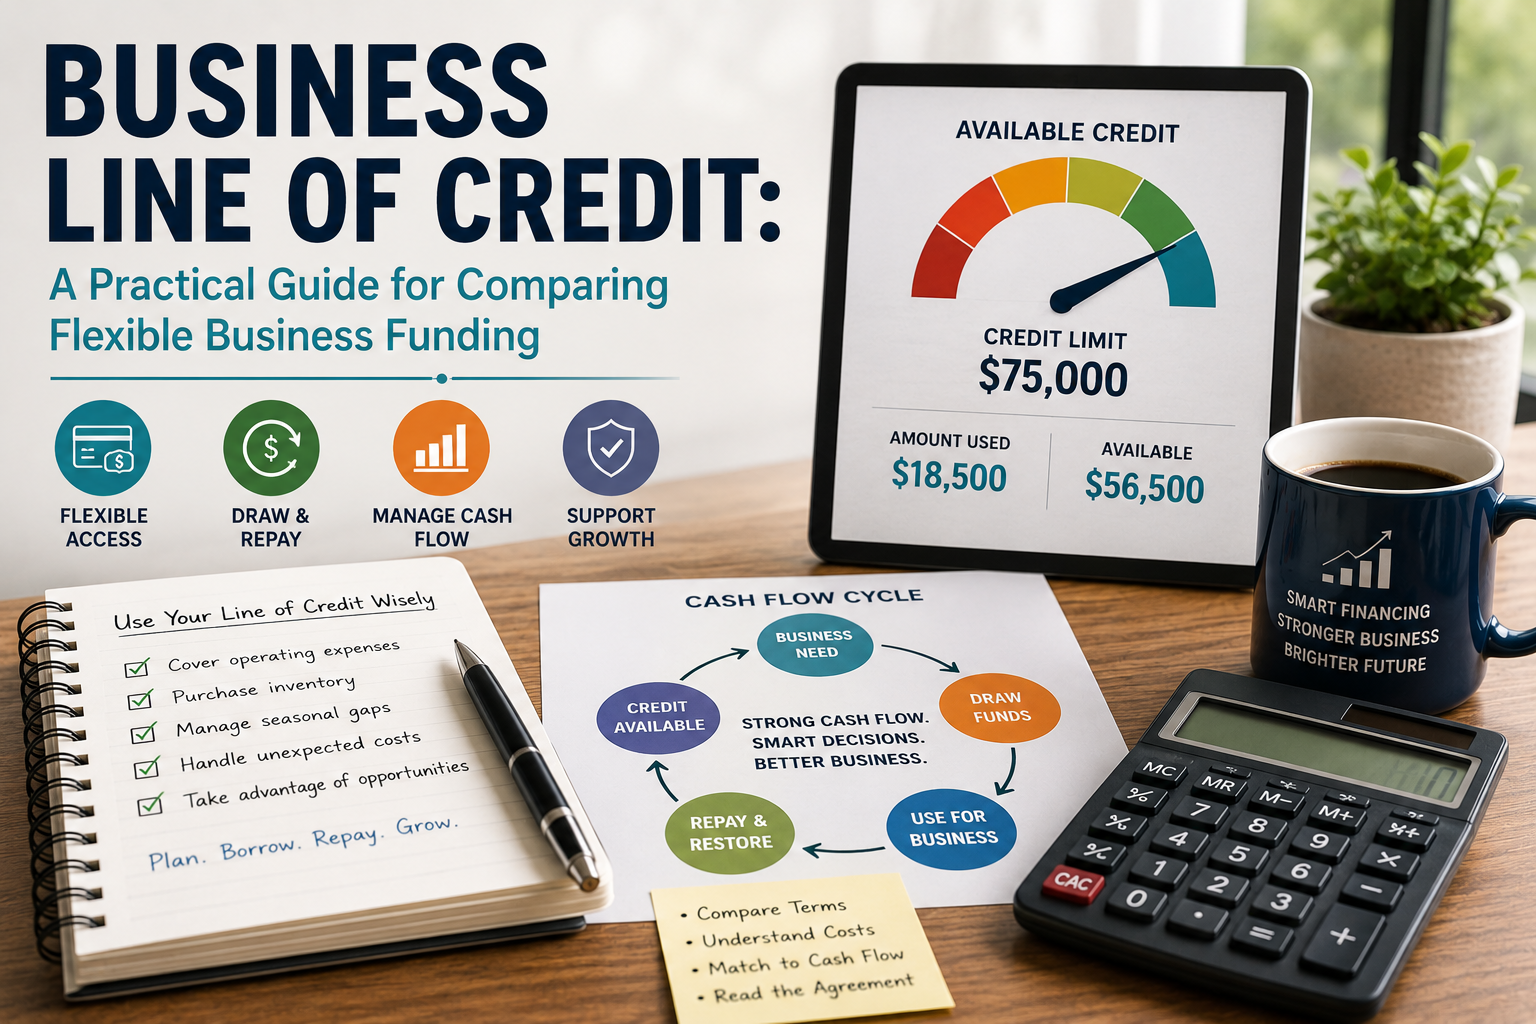
A business line of credit gives a company access to an approved borrowing limit that it can draw from when money is actually needed instead of receiving one compulsory lump sum upfront. With a revolving facility, principal that is repaid may become available to borrow again, subject to the lender’s rules and continued account eligibility.
That flexibility can make a business line of credit useful for inventory, supplier payments, seasonal expenses, temporary receivables gaps, repairs, payroll timing and other short-term working-capital needs.
But approval is not the main decision.
The real question is whether the business can use the line for a specific, temporary purpose, repay each draw from an identifiable source of cash and avoid turning flexible credit into permanent operating debt.
A serious comparison should therefore examine the amount actually needed, credit limit, amount drawn, interest or APR where provided, fees, payment frequency, repayment period, remaining available credit, collateral, personal guarantees, lender review rights, renewal conditions and the cash expected to repay the borrowing.
Educational note: Kevanzo.com provides general business-financing education only. Kevanzo is not a lender, broker, loan marketplace, financial adviser, attorney, accountant or approval service. Financing products, rates, fees, credit limits, underwriting standards and availability vary. Review the complete written financing agreement before borrowing.
Business Line of Credit: Quick Decision Summary
A business line of credit may be worth comparing when the funding requirement is recurring or unpredictable, the business does not need the entire approved amount immediately and there is a reasonably identifiable way to repay each draw.
It deserves considerably more caution when the business continually needs new draws to pay ordinary expenses, the outstanding balance rarely falls, repayment depends on optimistic future growth or the business would struggle to operate if the lender reduced or froze the available credit.
| Question | Stronger sign | Warning sign |
|---|---|---|
| What is the money for? | Specific temporary expense | General shortage of cash |
| How much is needed? | Measured draw amount | Borrowing the maximum because it is available |
| What repays the draw? | Identifiable receivable, sales cycle or operating cash | No clear repayment source |
| How often will credit be used? | Occasional or cyclical | Constantly |
| Does the balance decline? | Regularly | Rarely |
| Can the business survive a slow month? | Yes, with cushion remaining | Repayment creates a cash deficit |
| What happens if the line is reduced? | Business can continue operating | Business depends on full availability |
The broader small business loans guide is useful when the business still needs to decide whether revolving credit, a term loan, SBA financing or another borrowing structure fits the underlying need.
What a Business Line of Credit Actually Means
A business line of credit is borrowing capacity rather than automatic cash.
Suppose a company is approved for a $100,000 line.
That does not necessarily mean $100,000 is deposited into its account.
The company might instead:
- draw $20,000 for inventory;
- repay $12,000 after customers purchase that inventory;
- later draw $10,000 for an emergency repair;
- repay the outstanding balance;
- and restore some or all of its available borrowing capacity.
The exact mechanics depend on the agreement.
A business line may contain rules covering the credit limit, minimum draws, interest, loan fees, draw fees, annual or maintenance fees, required payments, maturity, repayment frequency, collateral, personal guarantees, renewal reviews, account suspension, limit reductions and default.
The headline limit therefore tells only part of the story.
The more important number is often:
How much will the business actually draw, and what will repay it?
The Kevanzo Draw-Purpose Test
Before making any draw, answer five questions.
1. What exact expense will the draw cover?
Avoid vague borrowing such as:
“We could use more cash.”
A stronger statement is:
“We need $22,000 to purchase seasonal inventory that is expected to convert into customer sales over the next 90 days.”
Specific borrowing is easier to evaluate than general borrowing.
2. Why is credit being used instead of existing cash?
A company may reasonably want to preserve an emergency reserve.
But borrowing still has a cost.
Compare the financing cost with the reason cash is being preserved.
3. What will repay this particular draw?
Possible repayment sources include customer invoice collections, inventory sales, contract payments, seasonal receipts or ordinary operating cash flow.
Each draw should ideally have its own repayment logic.
4. When should the balance decline?
Temporary credit that never becomes temporary debt is a warning sign.
Estimate when the borrowed amount should begin falling and when it should reasonably be cleared.
5. What happens if the expected cash arrives late?
Run a delay scenario.
What happens if a customer is 30 days late, inventory sells slowly, costs rise or another unexpected expense occurs?
A business line of credit should create flexibility, not eliminate the company’s remaining margin for error.
Revolving Credit Versus a One-Time Business Loan
The defining advantage of many business lines of credit is reuse.
A revolving structure generally allows available credit to replenish as principal is repaid, subject to lender rules, continuing eligibility and the agreement.
A traditional term loan generally works differently.
The business receives one lump sum and repays that specific borrowing over an agreed period.
That distinction matters.
A line may fit:
- recurring inventory purchases;
- uneven receivables;
- seasonal operating costs;
- repeat project expenses;
- short cash-flow gaps;
- unexpected repairs.
A term loan may be easier to evaluate for:
- one known equipment purchase;
- a defined renovation;
- a fixed acquisition cost;
- a one-time expansion;
- another project where the total amount is known in advance.
The financing structure should match the business problem.
The Kevanzo Draw-to-Repayment Cycle
A healthier revolving-credit cycle often looks like this:
business need → draw → productive use → cash returns → repayment → available credit restored
For example:
A retailer draws $25,000.
The money buys seasonal inventory.
Customers purchase the inventory.
Cash returns to the business.
The outstanding balance is reduced.
Credit capacity becomes available again according to the agreement.
Compare that with:
draw → ordinary bills → partial repayment → another draw → ordinary bills → another draw
The second pattern may indicate that the line is no longer solving a timing problem.
It may be financing an ongoing operating deficit.
That is a very different risk.
The $10K–$100K Business Line of Credit Decision Zone
Credit limit and actual borrowing should always be separated.
Suppose the business is approved for a $100,000 revolving line.
| Amount drawn | Remaining nominal capacity before other adjustments | Utilization of $100,000 line |
|---|---|---|
| $10,000 | $90,000 | 10% |
| $25,000 | $75,000 | 25% |
| $50,000 | $50,000 | 50% |
| $75,000 | $25,000 | 75% |
| $100,000 | $0 | 100% |
A higher approved limit can provide useful backup capacity.
It does not mean the business should deliberately use all of it.
Drawing $25,000 to solve a $25,000 problem is fundamentally different from drawing $100,000 simply because the lender made that amount available.
The unused portion can provide flexibility.
The borrowed portion creates repayment obligations.
Approval Limit Is Not a Spending Target
An approval number is a lender decision.
A draw amount should be a business decision.
Before using the facility, record:
Approved limit: $________
Actual funding need: $________
Proposed draw: $________
Expected repayment source: ________
Expected repayment period: ________
If the proposed draw is materially larger than the actual need, ask what productive purpose justifies the difference.
If there is no good answer, the business may simply be increasing debt exposure.
The Kevanzo Total-Cost Normalizer
Business line of credit offers can be difficult to compare because providers may present pricing differently.
One lender may show APR.
Another may quote an interest rate.
Another may disclose a fixed fee for each draw.
Another may have annual, maintenance, origination or other charges.
The Federal Reserve’s 2026 Small Business Credit Survey illustrates why full-cost comparison matters. Among businesses that borrowed from online lenders, 60% reported that actual borrowing costs were higher than expected, compared with 37% of borrowers at small banks and 32% at large banks. The survey was a nationwide convenience sample of 6,525 employer firms, so it should be interpreted with that methodology in mind.
For every offer, record these numbers:
- Approved credit limit.
- Planned draw.
- Cash actually received.
- Interest or APR, if disclosed.
- Draw or origination fees.
- Annual or maintenance fees.
- Total expected repayment.
- Required payment amount.
- Payment frequency.
- Remaining available credit after the draw.
Then ask:
How much usable cash does the business actually receive?
How much money must leave the business in total?
How quickly does that money have to leave?
That is more useful than comparing one advertised percentage in isolation.
A simple hypothetical comparison
Suppose two lenders each provide a $25,000 draw.
Offer A
Cash received: $25,000
Total repayment under the quoted schedule: $27,000
Financing cost: $2,000
Payment frequency: monthly
Repayment period: six months
Offer B
Cash received: $25,000
Total repayment under the quoted schedule: $28,600
Financing cost: $3,600
Payment frequency: weekly
Repayment period: 26 weeks
Offer B costs $1,600 more in this simplified example and also removes cash from the business much more frequently.
The simple cost percentages in an example like this are not substitutes for APR. When an APR is provided, use it. The purpose of the exercise is to make the total cash obligation visible.
Current U.S. Business Line of Credit Market Context
Business lines of credit remain an important part of the U.S. small-business financing market.
The Federal Reserve Bank of Kansas City reported that new small-business lending increased year over year in the first quarter of 2026, driven partly by increased new lines of credit at large and midsize banks. Its bank survey also reported that variable-rate lines represented about 91% of total credit-line usage among respondents.
That second point is important.
If a line carries a variable rate, the cost can change even when the outstanding principal does not.
A business should therefore stress-test both:
more borrowing
and
a higher borrowing rate.
The 2026 Small Business Credit Survey found that 38% of employer firms surveyed had applied for a loan, line of credit or merchant cash advance in the prior 12 months. It also found that 42% of applicants received the full amount sought, 36% received some or most and 22% received none.
Approval should therefore never be assumed merely because a business appears to meet one published requirement.
Current Business Line of Credit Examples — Checked October 1, 2026
The following section is a market snapshot, not a ranking or recommendation. Terms can change. Eligibility depends on underwriting. Always verify the lender’s current first-party disclosures before applying.
| Provider and product | Published line size | Published structure | Selected current facts |
|---|---|---|---|
| Bank of America Business Advantage Credit Line | $10,000–$250,000 | Unsecured revolving line with annual renewal | Bank of America lists a $150 annual fee, waived in year one; at least two years under current ownership; at least $100,000 in prior-year business revenue; and says personal credit above 700 FICO is typically required. Interest is charged on the outstanding balance. |
| Wells Fargo BusinessLine | $10,000–$150,000 | Unsecured revolving credit | Wells Fargo currently advertises rates as low as Prime + 1.75%. The annual fee is waived in the first year, then listed as $95 for $10,000–$25,000 lines and $175 for larger lines. Personal guarantees are required. |
| Bluevine Line of Credit | $1,000–$250,000 | Revolving line with weekly or monthly repayment options | Bluevine says it has no setup, subscription, maintenance, termination or unused-funds fees. Pricing depends on underwriting. Its first-party guidance currently lists 625+ FICO, at least $10,000 monthly revenue and 12+ months in business for applicants. |
| OnDeck Line of Credit | $6,000–$200,000 | Revolving credit; 12-, 18- or 24-month repayment options | OnDeck lists weekly or monthly payments and application requirements including one year in business, $100,000 annual revenue and a 625 personal FICO score. Its site reports an average 59.8% APR for lines originated in the half-year ending June 30, 2026. |
| American Express Business Line of Credit | $2,000–$250,000, with larger lines possible for some customers | Individual draws become separate loans; eligible terms may include 6, 12, 18 or 24 months | American Express says pricing and available terms depend on the customer’s financial profile. Its current terms state that loans are secured by borrower assets and require a personal guarantee. |
The point of this table is not to identify one universal “best” business line of credit.
The structures are too different for that.
One business may care most about monthly rather than weekly repayment.
Another may place greater value on a bank relationship.
Another may need a smaller minimum line.
Another may prefer a facility without a recurring account fee.
Another may be unable to meet a lender’s operating-history or revenue requirement.
The correct comparison happens at the written-offer level.
Readers who want to examine the differences between banks, online financing companies and SBA-participating lenders can also review Kevanzo’s guide to small business loan lenders.
What Lenders May Review
Business line of credit requirements vary considerably.
Common underwriting factors can include:
- personal credit;
- business credit;
- time in business;
- annual or monthly revenue;
- cash flow;
- profitability;
- existing debt;
- debt-payment history;
- industry;
- bank-account activity;
- ownership;
- requested amount;
- intended use;
- collateral;
- guarantees;
- receivables;
- financial statements.
No single credit score, revenue threshold or time-in-business requirement applies to every lender.
This is why businesses should avoid articles that present one underwriting number as though it defines the entire market.
If credit is a particular concern, Kevanzo’s business loans for bad credit guide explores the broader relationship between weaker credit, affordability, documentation and lender underwriting.
The Kevanzo Qualification Matrix
Before applying, classify the business across five areas.
Operating history
How long has the business operated under the present ownership?
Longer operating history can give a lender more financial evidence to examine.
Revenue
Is revenue consistent enough to support the proposed borrowing?
High revenue by itself does not guarantee strong repayment capacity.
Cash flow
How much cash remains after normal operating expenses and existing debt payments?
This is often more important to the owner than headline revenue.
Credit profile
What do the relevant personal and business credit records show?
Review them for accuracy before financing becomes urgent.
Existing obligations
List every outstanding loan, lease, credit card, line of credit and other material financial obligation.
A new credit line has to coexist with all of them.
Documents Worth Preparing Before Applying
Requirements vary, but businesses may be asked for:
- business formation and registration information;
- ownership details;
- tax identification information;
- recent bank statements;
- profit and loss statements;
- balance sheets;
- tax returns;
- accounts receivable aging;
- accounts payable aging;
- existing debt schedules;
- identification;
- collateral information;
- contracts or purchase orders;
- invoices;
- explanation of the intended use of funds.
Preparing accurate records before applying can make it easier to compare offers and understand what the lender is evaluating.
Documentation does not guarantee approval.
It reduces unnecessary uncertainty.
Business Line of Credit Pre Approval
Businesses may receive advertisements or messages using phrases such as:
pre-approved
pre-qualified
eligible
up to
These expressions should not automatically be interpreted as a final lending commitment.
Final underwriting may still require verification of revenue, credit, bank activity, ownership, financial statements, collateral or other information.
For a step-by-step explanation of conditional offers, credit checks and final underwriting, see Kevanzo’s business line of credit pre approval guide. Remember that pre approval is not a final financing agreement.
The important question is:
What has actually been approved, and what remains subject to verification?
Repayment Frequency Can Matter as Much as Rate
A financing offer can look affordable on an annual basis but create substantial pressure if payments leave the business every week.
Compare:
$4,000 once per month
with
roughly $1,000 every week.
Those schedules can produce different operating effects even when the annual cash outflow appears similar.
A business with uneven receivables may find weekly withdrawals especially important to test.
Before accepting an offer, map required repayments against the company’s real cash-receipt cycle.
The Kevanzo Slow-Month Stress Test
Suppose normal monthly cash inflow is:
$100,000
Ordinary operating outflow:
$88,000
Cash remaining before new financing:
$12,000
New credit-line repayments:
$4,000
Normal remaining cushion:
$8,000
Now suppose a slower month produces only $82,000 of cash inflow while operating outflow falls to $80,000.
Before the new debt payment, only $2,000 remains.
After a $4,000 financing payment:
-$2,000
The line that appeared manageable during a normal month now produces a cash deficit.
The numbers are hypothetical, but the test is extremely practical.
Do not ask only:
Can the business make the payment during an average month?
Ask:
Can the business make it during a realistic slow month?
Interest, APR and Variable Rates
Interest rate and APR are related but not identical concepts.
APR can be useful because it attempts to express borrowing cost on an annualized basis and may incorporate certain fees.
But not every business financing product presents pricing in the same format.
A line may also carry a variable rate tied to a benchmark such as Prime.
Because the Kansas City Fed’s Q1 2026 survey found variable-rate lines dominated bank credit-line usage among its respondents, businesses should pay close attention to how the agreement permits rates to change.
Before borrowing, ask:
- Is the rate fixed or variable?
- What benchmark is used?
- What margin is added?
- How often can the rate change?
- Is there a floor?
- Is there a maximum?
- When does interest begin?
- How is interest calculated?
- Does early repayment reduce cost?
Never compare only the lowest advertised rate.
Compare the rate the business actually receives.
Business Line of Credit Fees
Possible fees may include:
- annual fees;
- maintenance fees;
- origination fees;
- draw fees;
- late fees;
- wire or transfer fees;
- unused-line fees;
- prepayment-related charges;
- renewal fees;
- documentation or servicing charges where permitted.
Not every lender charges all of these.
Some charge very few.
The business should still review the complete agreement rather than relying on marketing copy.
The Federal Trade Commission has previously taken action involving small-business financing marketing where it alleged that borrowers received less cash than advertising suggested because of fees and where contract terms conflicted with claims concerning personal guarantees. The FTC’s broader guidance is straightforward: examine the complete offer and ask questions when terms are unclear.
The Kevanzo Eight-Number Credit-Line Comparison
Before accepting a facility, put these eight numbers on one page.
1. Credit limit
Maximum borrowing capacity currently offered.
2. Planned initial draw
What the business actually expects to borrow first.
3. Net cash received
The amount that reaches the business after any deductions.
4. Interest or APR
Use the actual offered figure rather than a promotional minimum whenever possible.
5. Account and draw fees
Record every known charge.
6. Required payment
How much cash must leave the business each time.
7. Payment frequency
Daily, weekly, monthly or another schedule.
8. Available credit after the draw
How much borrowing capacity remains for genuine future needs.
If two offers cannot be clearly compared across these eight numbers, keep investigating until they can.
Secured Versus Unsecured Business Lines of Credit
A secured line generally involves collateral or a security interest.
An unsecured line generally does not require a specifically pledged asset in the same way.
But unsecured does not mean risk-free.
An unsecured facility can still involve:
- personal guarantees;
- UCC filings;
- contractual lender remedies;
- default provisions;
- account freezes;
- acceleration clauses;
- legal collection rights.
The 2026 Small Business Credit Survey found that, among firms with outstanding debt, 59% reported using a personal guarantee to secure debt and 51% reported using business assets. Those figures apply to debt generally in the survey, not specifically to every line-of-credit product, but they show why owner exposure deserves serious attention.
Kevanzo’s dedicated unsecured business line of credit guide goes further into collateral, guarantees and owner exposure.
Personal Guarantees Require First-Class Attention
A personal guarantee can create obligations beyond the business entity itself.
Before signing, determine:
- who is guaranteeing the debt;
- whether every major owner must guarantee;
- whether the guarantee is limited or unlimited;
- what events trigger liability;
- whether the guarantee continues after renewal;
- what happens if ownership changes;
- what rights the lender has following default.
Do not assume “unsecured” means “no personal exposure.”
Read the actual guarantee language.
The Kevanzo Guarantee-Exposure Test
Compare:
business value created by the credit line
against:
owner exposure created by the guarantee
Then ask:
Is that trade-off justified?
A slightly cheaper financing offer is not automatically better if it creates substantially greater personal exposure or gives the lender materially broader remedies.
Renewal and Limit-Reduction Risk
A line of credit is valuable partly because the business expects funds to remain available.
That expectation can become dangerous if the business begins treating the entire limit as permanent working capital.
Depending on the agreement, a lender may have rights to review the facility, reduce available credit, change terms, suspend draws, require additional information, decline renewal or close the line.
That creates availability risk.
A business should not become so dependent on the facility that a reduction in credit immediately threatens payroll, suppliers or ordinary operations.
The Kevanzo Renewal Readiness Test
Before renewal or periodic review, examine:
Outstanding balance: Is it lower, higher or unchanged?
Repayment history: Have payments been made as required?
Cash-flow trend: Is operating cash improving or deteriorating?
Revenue trend: Is the company becoming stronger or weaker?
Existing debt: Has total leverage increased?
Financial records: Can current information be produced quickly?
Alternative liquidity: Could the company operate if the line disappeared?
The last question matters most.
Flexible credit is more useful when the business controls the line.
It becomes riskier when the line controls the business.
The Kevanzo 90-Day Line Review
Every 90 days, ask:
Has the balance increased or decreased?
A falling balance suggests repayment is occurring.
A permanently high balance deserves investigation.
How many draws were made?
Frequent draws can indicate repeated operating pressure.
What did each draw fund?
Every material draw should have a business purpose.
What cash repaid those draws?
Identify the source.
How much has the facility cost?
Include interest and fees.
How much unused borrowing capacity remains?
A line that is continually at its limit has lost much of its flexibility.
Business Line of Credit for Working Capital
One of the clearest uses for revolving credit is temporary working-capital timing.
A business may pay suppliers today while customer receipts arrive later.
It may purchase inventory before a seasonal selling period.
It may fund materials before a contract milestone payment.
A line can bridge that gap.
But the underlying business activity should still create enough cash to repay the draw.
For a deeper product-versus-purpose comparison, see working-capital loans for small business.
Seven Business Line of Credit Scenarios
Seasonal retailer
A retailer needs $30,000 of inventory before its busiest quarter.
A line may allow the business to draw when inventory is ordered and repay after sales occur.
The key risk is disappointing sales.
Contractor awaiting progress payments
A contractor must buy materials now but will receive a customer payment after reaching a project milestone.
The key risk is a delayed milestone or disputed invoice.
Professional-services company
A consulting firm invoices large clients on 30- or 60-day terms but must pay staff sooner.
A credit line may bridge that timing mismatch.
The company should still improve billing and collection practices rather than permanently financing slow receivables.
Emergency equipment repair
An essential machine fails and costs $15,000 to repair.
A line can provide immediate liquidity.
The business should compare the likely repayment period with a short-term business loan if the need is clearly one-time.
Repeat inventory purchases
A wholesaler repeatedly purchases inventory before customer orders are settled.
Revolving credit may fit better than applying for separate loans repeatedly.
Major expansion
A company wants to open a second facility requiring substantial one-time capital.
A term loan or another form of business financing may fit the long-lived project better than continually revolving short-term credit.
Business covering persistent losses
A company is losing $18,000 every month and draws repeatedly merely to remain open.
A line of credit does not fix the underlying economics.
Unless profitability or cash generation changes, additional borrowing can simply postpone the problem while increasing debt.
When a Business Line of Credit May Be the Wrong Product
A revolving line deserves caution when:
- the need is one large, fixed purchase;
- the business expects to carry the full balance for years;
- weekly repayments would strain cash flow;
- the business has no identifiable repayment source;
- borrowing is covering persistent losses;
- the line is being used to repay another line repeatedly;
- the company cannot operate without permanent access to the maximum limit;
- collateral or guarantee exposure is disproportionate to the benefit;
- a term structure would better match the life of the asset being financed.
Choosing not to use a business line of credit can be a good financing decision.
Business Line of Credit Versus Other Financing
| Financing structure | Often worth comparing for | Main question |
|---|---|---|
| Business line of credit | Recurring or unpredictable short-term needs | Can each draw be repaid and reused responsibly? |
| Term loan | One known lump-sum need | Does the repayment term match the asset or project? |
| Working-capital loan | Operating expenses and temporary cash needs | How quickly will operating cash repay it? |
| Business credit card | Smaller purchases and payment convenience | What happens if balances revolve? |
| Equipment financing | Equipment purchase | Does the asset support the obligation? |
| Invoice financing | Cash trapped in receivables | What does early access to the invoice value cost? |
| SBA-backed financing | Eligible business purposes requiring an SBA-supported structure | Does the program and lender process fit the need? |
For businesses considering government-supported financing, Kevanzo’s SBA loans guide explains the wider SBA lending structure.
SBA Revolving Credit Options
SBA financing is not limited to conventional lump-sum loans.
The SBA states that revolving credit is permitted under programs including SBA Express, Export Express and CAPLines. Its Working Capital CAPLine is designed around recurring and short-term needs, with repayment tied to conversion of short-term assets into cash.
The SBA also currently operates its 7(a) Working Capital Pilot, which provides monitored lines of credit of up to $5 million for eligible businesses and can support contract or project financing as well as borrowing against accounts receivable or inventory.
These structures have different requirements from ordinary commercial lines.
Do not assume an SBA-supported line and a conventional online line are interchangeable.
Business Line of Credit Red Flags
Investigate further when:
- advertising focuses heavily on approval speed but provides little cost information;
- the company cannot explain total repayment;
- the business is pressured to sign immediately;
- important fees appear only late in the process;
- the amount actually received is lower than expected;
- “unsecured” is presented as though no guarantee or security rights exist;
- payment frequency is unclear;
- renewal rules are vague;
- variable-rate mechanics are not explained;
- the business is encouraged to borrow more than it needs;
- the borrower cannot explain how the debt will be repaid;
- financing depends on unrealistic future revenue.
If the offer cannot be understood before signing, it is not ready to be accepted.
Questions to Ask Before Accepting a Business Line of Credit
Ask the lender or provider:
- What is the exact credit limit?
- What is the minimum draw?
- Is the facility revolving?
- Does repaid principal automatically restore availability?
- What interest rate or pricing method applies?
- Is the rate fixed or variable?
- What APR is provided, if applicable?
- What fees apply?
- How much cash will the business actually receive from a draw?
- What payment amount is required?
- How often are payments collected?
- Can the business repay early?
- Does early repayment reduce the cost?
- Is collateral required?
- Is there a personal guarantee?
- Will a UCC filing be made?
- Can the credit limit be reduced?
- Can further draws be frozen?
- Does the line require renewal?
- What happens at maturity?
- What constitutes default?
- Are additional draws subject to new review?
- What information must the business continue providing?
- What happens if a payment is late?
- What is the total expected cost of the specific draw being considered?
Get important answers in writing.
The Kevanzo 15-Point Business Line of Credit Check
Before borrowing, complete this final check.
1. Purpose
What precise business problem is being solved?
2. Credit limit
What is the maximum currently available?
3. Planned draw
How much will actually be borrowed?
4. Draw purpose
Where will the money go?
5. Repayment source
What cash will pay it back?
6. Repayment timing
When should the balance begin falling?
7. Interest or APR
What actual pricing applies?
8. Fees
What other costs exist?
9. Payment frequency
How often will money leave the business?
10. Available capacity
How much of the line remains after the draw?
11. Slow-month test
Does repayment still work when revenue disappoints?
12. Security
What collateral, guarantees or lender rights apply?
13. Renewal risk
What happens if the facility changes or disappears?
14. Alternative financing
Would another structure fit better?
15. Exit strategy
How and when will the business stop relying on the debt?
If several of these questions cannot be answered, the financing decision is not finished.
Practical Next Steps
First, define the funding problem.
Second, determine the amount genuinely needed.
Third, identify the repayment source before borrowing.
Fourth, prepare accurate financial documents.
Fifth, compare several realistic financing structures rather than focusing only on approval.
Sixth, normalize each offer by net cash received, total financing cost, payment frequency, security obligations and remaining credit capacity.
Seventh, run the slow-month stress test.
Eighth, read the complete written agreement.
Ninth, borrow only when the financing solves a measurable business need whose expected benefit justifies its cost and risk.
Final Takeaway
A business line of credit can be one of the most flexible forms of business financing because the company can potentially draw funds when needed, repay them and restore borrowing capacity.
That flexibility is also exactly why discipline matters.
The strongest business line of credit is not automatically the facility with the largest limit, fastest funding or most attractive advertised rate.
It is the facility whose:
draw size matches the real need;
complete cost is understood;
payment frequency fits actual cash flow;
collateral and guarantee exposure are acceptable;
renewal and availability risks are understood;
and
repayment source exists before the money is borrowed.
The central question is therefore not:
How much can this business borrow?
It is:
How much should this business draw, what will the draw accomplish, what will it truly cost and what specific cash will repay it?
That is the decision a serious borrower should answer before accepting any business line of credit.
Frequently Asked Questions About a Business Line of Credit
What is a business line of credit?
It is a financing facility that gives a business access to an approved borrowing limit. The business may draw funds as needed subject to the agreement rather than necessarily receiving the full limit upfront.
Is a business line of credit the same as a business loan?
Not usually. A term loan typically provides one lump sum. A revolving line may allow repeated draws and may restore available credit as principal is repaid.
Is interest charged on the entire credit limit?
Many lines charge interest on the amount actually borrowed rather than the unused limit, but account fees or other charges may still apply. Always check the agreement.
Is every business line of credit revolving?
No. Some facilities can contain limited draw periods, maturity dates or other restrictions. Verify whether repaid principal becomes available again.
What can a business line of credit be used for?
Common uses include inventory, supplier payments, receivables timing, seasonal expenses, repairs and other working-capital needs, subject to lender restrictions.
How much should a business draw?
Ideally, only the amount justified by the actual business need and supported by a realistic repayment source. The approved limit should not be treated as a spending target.
Is an unsecured business line of credit risk-free?
No. Unsecured financing can still involve personal guarantees, UCC filings, contractual remedies and other obligations.
Does pre approval guarantee funding?
No. Preliminary approval or qualification may still be subject to underwriting, document verification and final terms.
Can a lender reduce a business line of credit?
Depending on the agreement, a lender may have rights concerning availability, account reviews, renewal, suspension or limit changes. Read those provisions carefully.
Is a business line of credit good for working capital?
It can be useful for temporary or recurring working-capital timing needs when the business has a clear repayment source. It is much less suitable as a permanent solution to ongoing operating losses.
Is a line of credit better than a term loan?
Neither is universally better. A line may suit recurring or uncertain needs. A term loan may fit a one-time expense with a known amount and repayment period.
What is the biggest risk of a business line of credit?
One major risk is allowing temporary borrowing to become permanent debt through continual redraws. Rate changes, frequent repayments, guarantees and lender availability decisions can create additional risks.
How should businesses compare lenders?
Compare the actual written offers, including usable cash, total cost, rates or APR, fees, payment frequency, term, collateral, guarantees, renewal conditions and lender rights—not merely the advertised maximum line.
When should a business stop using a credit line?
Reconsider the facility if the balance no longer falls, new draws are needed simply to make ordinary expenses, repayment depends on unrealistic revenue or the business cannot function without constantly using the maximum line.
Authoritative Resources
For current U.S. small-business credit conditions, the Federal Reserve Banks’ Small Business Credit Survey provides nationwide financing data and borrower-experience findings.
The Federal Reserve Bank of Kansas City publishes quarterly information about bank small-business lending and credit-line conditions.
The U.S. Small Business Administration explains SBA 7(a), CAPLines and other government-supported financing structures.
The Federal Trade Commission publishes business guidance concerning financing claims, contract terms and borrower due diligence.
Author Bio
Kevanzo Editorial Team
Kevanzo Editorial Team creates practical, plain-English educational resources for U.S. business owners comparing business financing, small business loans, business lines of credit, lender requirements, borrowing costs, repayment structures, cash-flow risk and responsible financing decisions.
Copyright Notice
© 2026 Kevanzo. All rights reserved.
This article is protected by copyright and may not be copied, scraped, spun, republished or used commercially without prior written permission from Kevanzo. Brief quotations may be used with clear attribution and a link to the original article.
Unauthorized bulk scraping, automated republication, content spinning or commercial reproduction is prohibited.
Educational Disclaimer
Kevanzo.com provides general educational information about business financing. Kevanzo is not a lender, broker, loan marketplace, financial adviser, attorney, accountant or approval service.
Nothing in this article constitutes financial, legal, tax, accounting, investment, lending or personalized business advice.
Rates, APRs, fees, credit limits, repayment terms, eligibility requirements, collateral requirements, guarantees, lender policies, renewal conditions, funding availability and financing products can change and vary according to the lender, borrower, business profile, industry, credit history, revenue, cash flow, location and other underwriting factors.
Current lender examples were checked against first-party information on October 1, 2026. They are provided for educational comparison only and are not rankings or endorsements. Verify all current terms directly with the provider before applying or accepting financing.
Business owners should read the complete financing agreement and consider obtaining advice from appropriately qualified professionals when necessary before making a borrowing decision.
Thanks for your comment. A business line of credit can be useful when a business wants flexible access to funds, but it is still important to compare draw fees, repayment timing, credit limits, and lender requirements before applying. Kevanzo shares general educational information only and cannot make personal finance, legal, or tax decisions for visitors.