SBA 7(a) Loans: $10K–$100K Rates, Requirements & Lenders
SBA 7(a) loans and small business financing

SBA 7(a) loans can be a strong option for eligible U.S. small businesses that need roughly $10,000 to $100,000 for working capital, equipment, inventory, qualifying debt refinancing, ownership changes, or other permitted business purposes. In this range, the financing will normally fall within the SBA’s 7(a) Small delivery method, but approval still depends on both … Explore loan terms and costs
Working Capital Loans for Small Business: How to Compare Cash Flow Funding Without Overstretching Repayments

Working Capital Loans for Small Business guide for comparing business funding and cash flow needs

Working Capital Loans for Small Business can help owners manage everyday operating needs when bills must be paid before enough customer cash arrives. They may be considered for inventory, payroll timing, supplier invoices, seasonal expenses, project costs, or temporary gaps between completing work and collecting revenue. But Working Capital Loans for Small Business should do … Explore loan terms and costs

Small Business Loans: Compare Rates, Lenders & Requirements

Small business loans comparison for U.S. business owners

Small business loans can help a company buy equipment, purchase inventory, cover working-capital needs, expand operations, refinance eligible business debt, or fund another defined business purpose. The important decision is not simply whether financing is available. It is whether the amount, structure, repayment schedule, cost, lender requirements, collateral exposure, and likely business benefit fit together. … Explore loan terms and costs

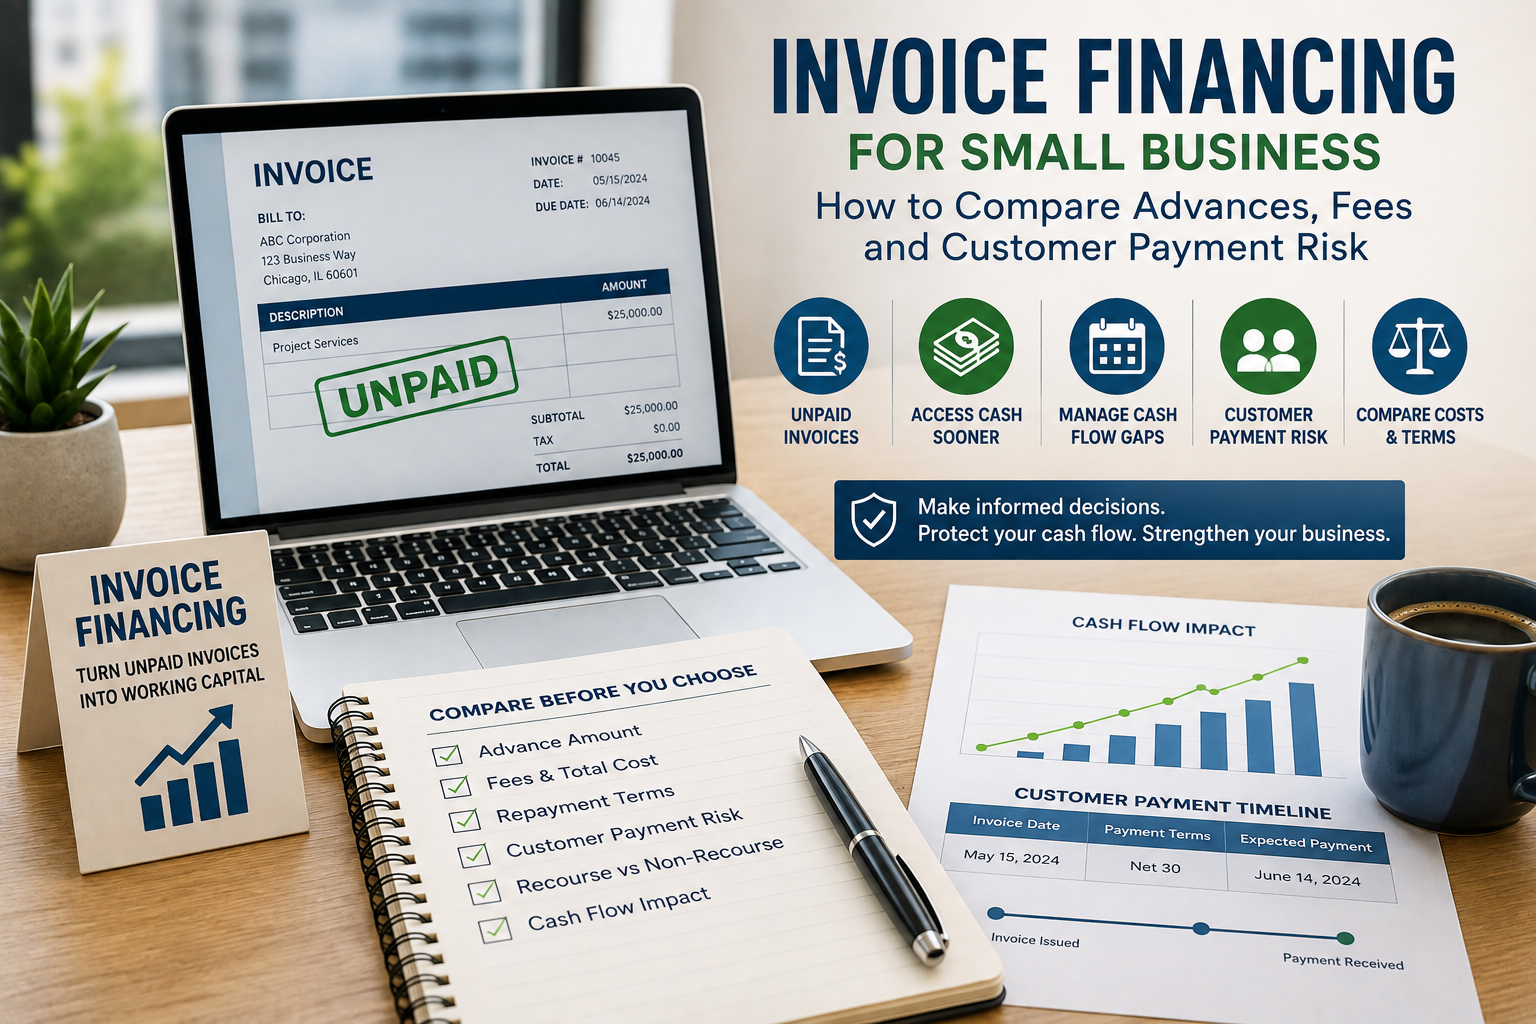
Invoice Financing for Small Business: How to Compare Advances, Fees and Customer Payment Risk

Invoice financing for small business showing unpaid invoices, advance funding, customer payment risk, fees, and cash flow management

Invoice financing for small business can help a company access cash that is tied up in unpaid customer invoices rather than waiting weeks or months for those customers to pay. For many businesses, the underlying problem is not lack of sales. It is timing. The business may have: but still be waiting for the actual … Explore loan terms and costs

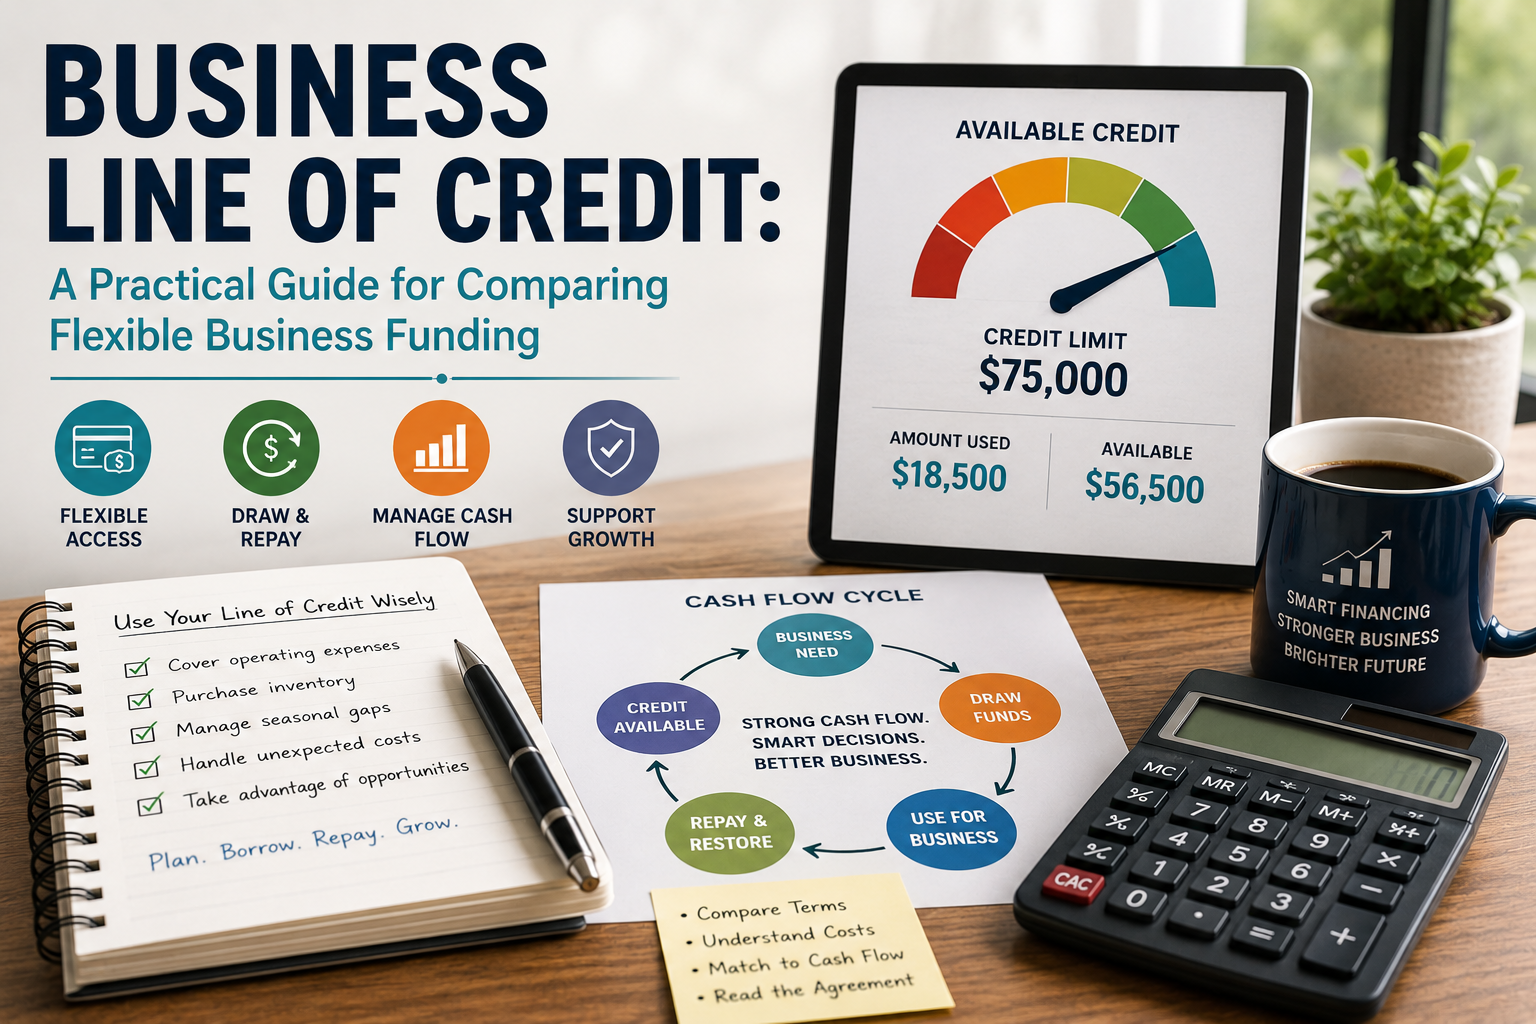
Business Line of Credit: How to Compare Rates, Limits, Lenders & Costs

Business line of credit showing flexible funding, available credit, draw and repayment, and cash flow management

A business line of credit gives a company access to an approved borrowing limit that it can draw from when money is actually needed instead of receiving one compulsory lump sum upfront. With a revolving facility, principal that is repaid may become available to borrow again, subject to the lender’s rules and continued account eligibility. … Explore loan terms and costs

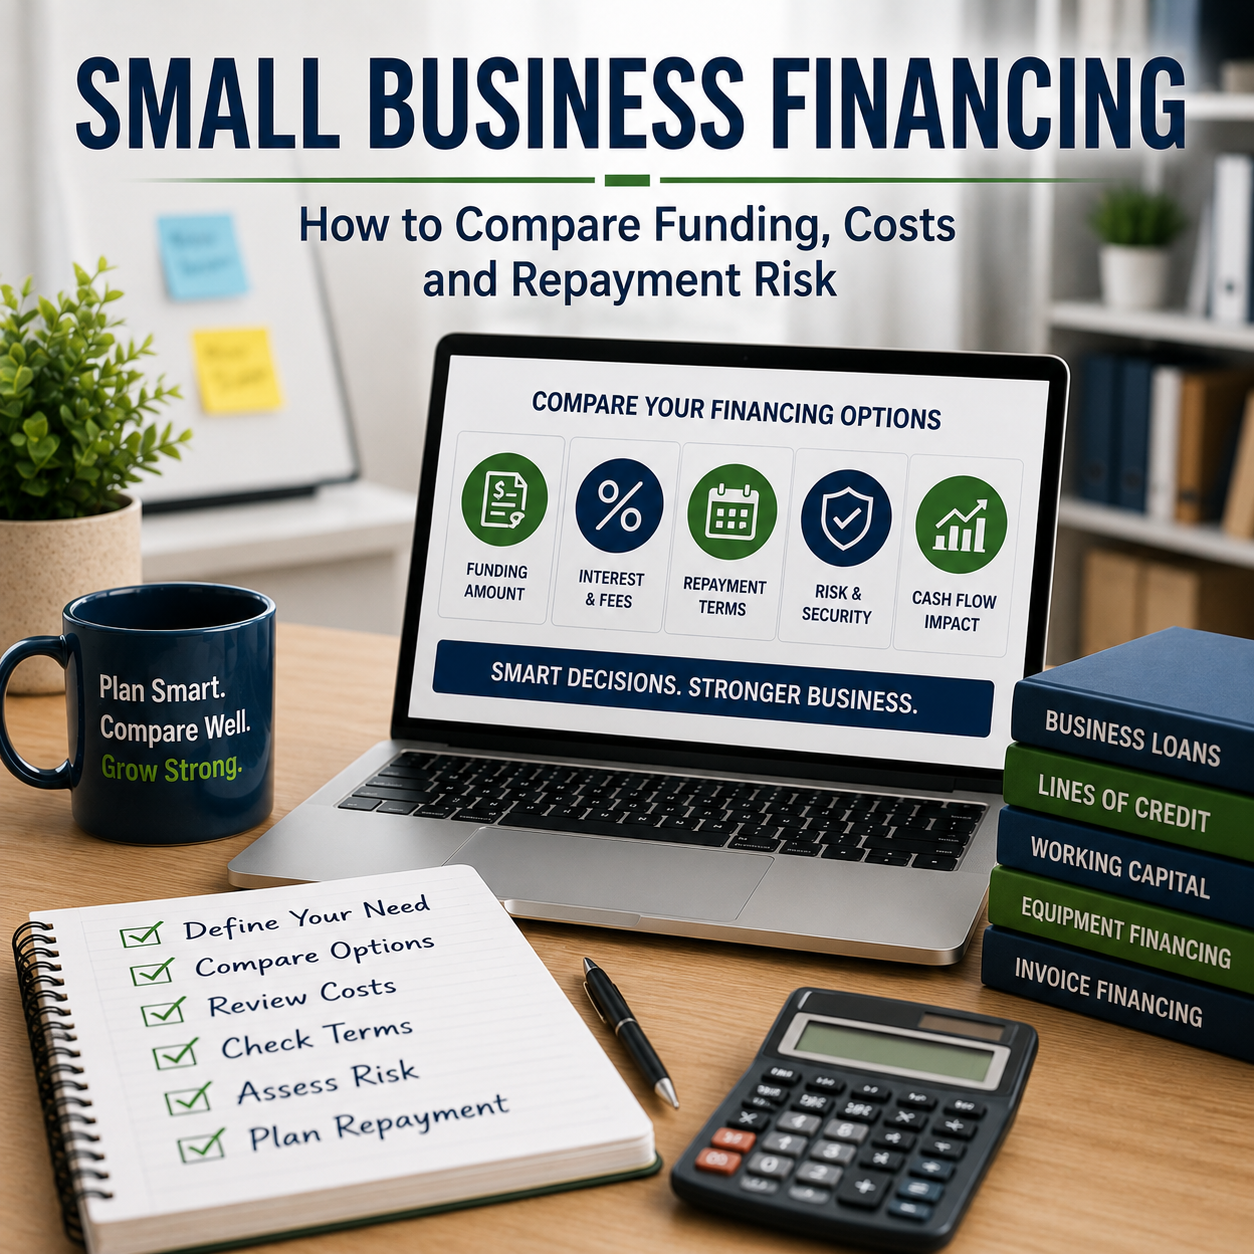
Small Business Financing: How to Compare Funding, Costs and Repayment Risk

Small Business Financing comparison showing funding options, borrowing costs, repayment terms, security, and cash flow impact

Small business financing gives companies access to capital for working capital, inventory, equipment, expansion, property, receivables gaps and other legitimate business needs. But financing is not one product, and the most important question is not simply: Can the business get funding? It is: Which financing structure solves the business problem without creating too much cost, … Explore loan terms and costs

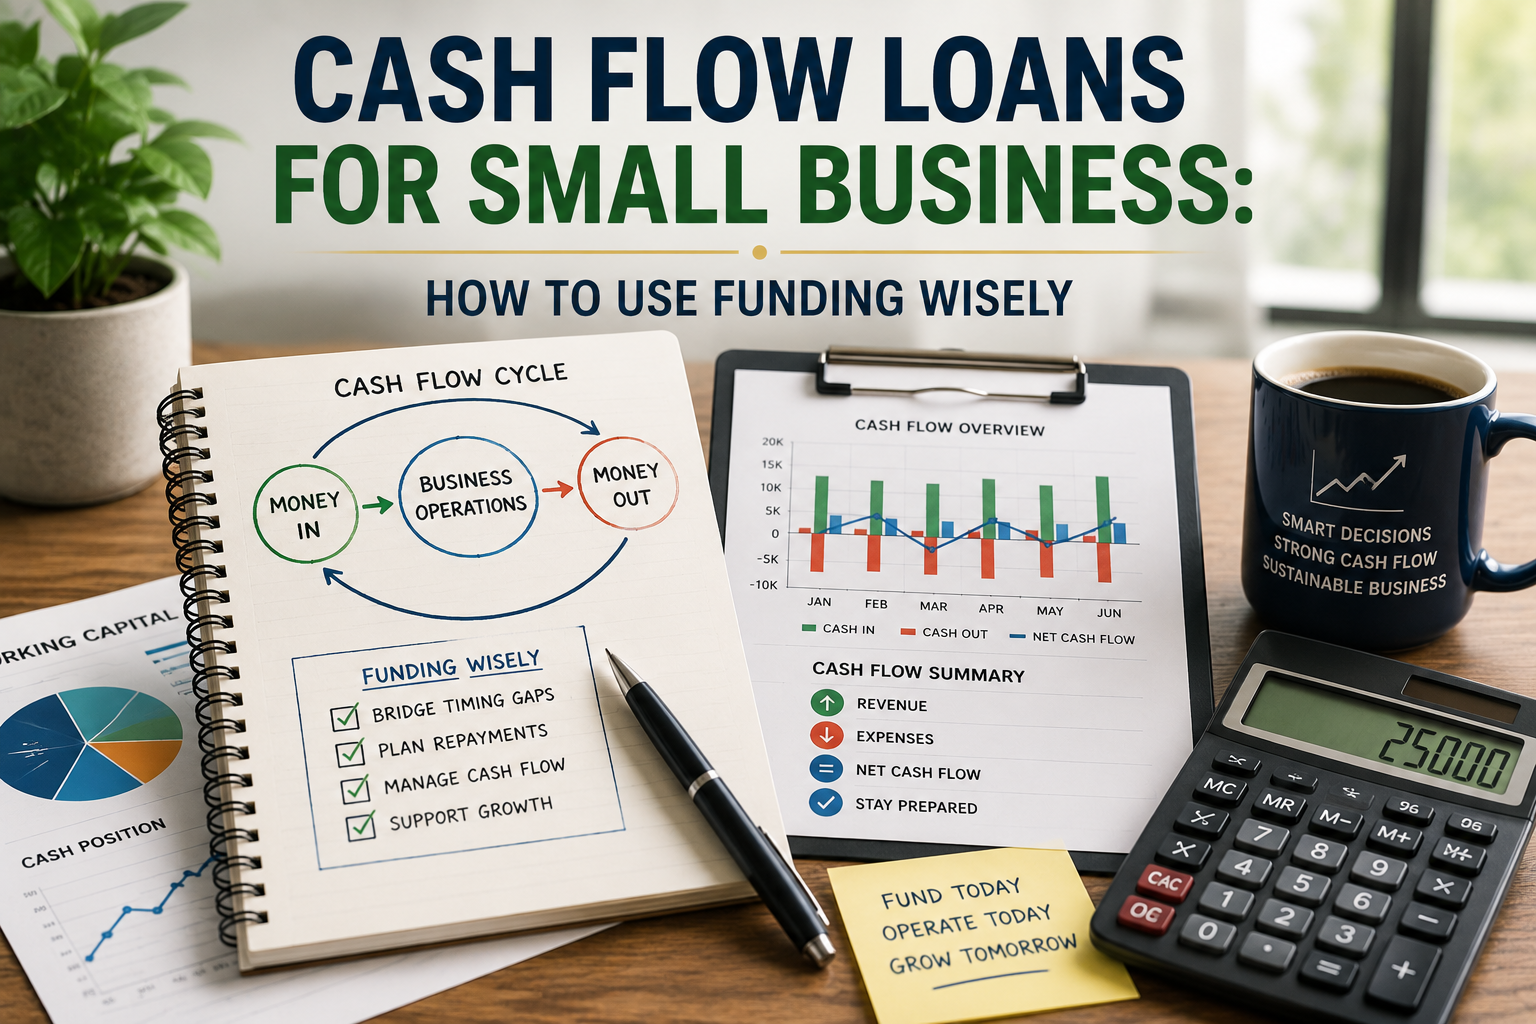
Cash Flow Loans for Small Business: How to Use Funding Wisely

Cash flow loans for small business showing funding, business expenses, repayment planning, and cash flow management

Cash flow loans for small business can help owners manage timing gaps between money leaving the business and money coming back in. A company may be profitable, have customers, and generate healthy sales while still experiencing periods when payroll, suppliers, inventory, rent, or other expenses become due before enough cash has been collected. That timing … Explore loan terms and costs

Business Debt Consolidation Loans: How to Compare Payments, Costs and Refinancing Risk

Business Debt Consolidation Loans comparison showing multiple business debts combined into one repayment structure with cost and refinancing risk review

Business Debt Consolidation Loans can help a company replace several existing business debts with one new financing arrangement. The attraction is easy to understand. Instead of managing: the business may end up with: one financing agreement → one repayment structure → one clearer debt plan But consolidation is not automatically an improvement. A lower scheduled … Explore loan terms and costs